Crank Up Your Wealth-Building Machine!

Property Money Making Machine

Owning a rental property can be a fantastic investment vehicle, helping you build wealth and financial stability over time.  That being said, many investors don’t fully understand the power of their investment and how to harness it.  I call it the magic of real estate investing. It goes way beyond just collecting a rent payment each month.

There are numerous ways to maximize the performance of your investment, some are obvious and some not-so-obvious.  The key is to take a longer view with real estate. The benefits of the investment might not be apparent for many years, but it is coming.  Given enough time, however, the results can be astounding.

So how can you crank up your wealth-building machine?

Cashflow

At a very basic level, the property should put a little money in your pocket each month.  This is a fundamental that shouldn’t be ignored.  It’s going to be difficult to build wealth when you have a property that is draining your finances.  Sure, you might be able to sell it at a profit someday, in the meantime, are you really getting ahead?

Equity-build

So many investors stress over having to make a mortgage payment, especially if the cashflow is weak.  But you need to think of it this way: every mortgage payment made is like forced savings for you.  Approximately 50% of a mortgage payment is Principle, which is equity that you build and retain.  It’s your storehouse of money and it’s amazing how quickly this accumulates over time.

Rent Increases

One thing that is pretty much certain: Rents will go up over time.  As the years pass, it’s amazing how much more rent you’ll be receiving for your property.  The key is to always serve the annual rent increase as permitted by law.  Many Landlords don’t want to “rock the boat” with a good Tenant by serving them with a rent increase. You need to keep in mind that your expenses are going up each year (ie. Property Taxes!) and most Tenants will expect a nominal rent increase each year, assuming the tenancy is going well.  Believe me, you don’t want to find yourself with a long-term Tenant paying the same rent as when they first signed the lease with you.  You might also obtain more substantial rent increases as you turn Tenants, ideally every couple of years.

Automate everything

Using technology to automate things like Utility and Tax payments don’t necessarily make you money, but they do make your life so much easier.  Automation also reduces the time-demand of real estate investing, which technically increases your profitability, considering that your time has a value.

Get help to make it passive

The beauty of real estate is that it can be a passive income stream, if you have the right team to support you.  You can hire-out many of the day-to-day functions, like Tenant Placement, rent collection, inspections, repairs and maintenance.  This comes at a cost, but your time and peace of mind might be more valuable.

Improvements to add Value

An investor should look beyond the month-to-month income and expenses and plan for reinvestment in the property to increase value.  Do not focus solely on the value of the property for when you sell or refinance it. You also need to look for re-investment areas in terms of it’s value in the eyes of a prospective Tenant.  Proper maintenance, updates and upgrades will attract high-quality Tenants and command a higher rental rate.

Appreciation

In general, real estate goes up in value over time.  You really don’t have to do anything for this to happen, but you can affect the amount of appreciation through effective maintenance and improvements.  Again, it’s a matter of looking beyond the month-to-month income and expenses and planning for the long-term.

Capital Cost Allowance

Under CRA rules, you have can claim capital depreciation to offset any potential taxable income realized from your rental property.  It is strongly advised you should consult a tax professional to learn the ins and outs of this approach. To give you some background, here is an article to read that gives a pretty thorough explanation.

In summary

Have questions about how to improve the performance of your investment property?  Feel free to reach out to us for a free, no-obligation consultation.  We are Real Estate Investors too, so we understand all elements of the business and how to maximize your investment.

Why is Cashflow Analysis so Important?

Cashflow Analysis for Property Management

Real Estate Property Investing 101:

No doubt about it, owning a rental property is an amazing experience and a great way to build wealth over time. It can also be a financial disaster if you don’t take the time to run the numbers before jumping in. This is why a Cashflow Analysis is important to include as an early step.

Understanding and doing a cashflow analysis of a property is critical to your success as an investor. Owning a rental property can be stressful enough. Adding pressure of a property draining your personal finances can push you past your limit.  Furthermore, your real estate portfolio must be sustainable and stable enough if you plan to grow it.  The alternative will make it very difficult to add additional properties to a money-losing portfolio.

I’ve often seen investors buy a property without knowing the numbers or considering if it makes financial sense to own the property at all.  Within months, they’re stressed-out and desperate to improve the situation.  Unfortunately, this scenario often ends with them selling the property altogether.

So, what is a cashflow analysis and how is it calculated? 

Cashflow Analysis Basics:

Basically, Cashflow is your Net Income…how much of the Revenue (Rental income) is left over after all the Expenses are paid.

A property can be either cashflow positive, cashflow neutral or have a negative cashflow.  This simply means it’s either making money, breaking-even or losing money.  Basically, a cashflow-positive property puts money in your pocket each month, while a cashflow-negative property takes money out of your pocket each month. 

Ideally, most investors want a property to be cashflow-positive.  However, this can depend on your situation and your goals.  I heard an interesting way of looking the cashflow of a property.  If you’re focused on the Cashflow, then you’re an Investor.  Alternatively, if you’re focused on Appreciation of the property, then you’re a Speculator.

Of course, we’re all speculators to some degree.  It is an inherent assumption that we want our properties to appreciate over time.  In the short term however, most of us need to be sure that the property is making money each month.  In some rare cases, it’s ok to carry a money-losing property, as long as there is some end-result that will offset the losses. But this is why Cashflow Analysis is so important at the start.

A Quick and Easy Cashflow Analysis

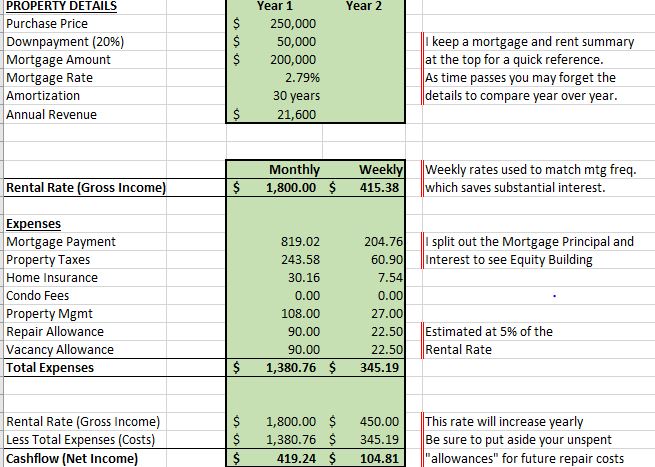
When I first got started in real estate investing, I created a simple spreadsheet. It is designed to run the numbers on each property that we were considering buying.  To this day, I still use that same spreadsheet and keep an updated copy for each property that we own.  That way, I can update the numbers, when we renew the mortgage, increase the rental rate or the appraised value of the property changes.

This is what it looks like:

Cash Flow Analysis

Here is a sample of this cashflow spreadsheet you can download now an update as you need.

Why is it important to understand Cashflow?

When buying an investment property, you need to know exactly what you’re getting yourself into.  I would say that’s one of the most important fundamentals of real estate investing.

Believe me, if you’re just starting out in real estate, you don’t want a property that is losing money each month.  As I mentioned before, owning a rental property can be stressful enough, without the added strain on your personal finances that a money-losing property will have.

Maybe losing $100 or $200 per month doesn’t sound like much, but this can quickly become much worse if there’s an increase in Mortgage Rates. Unplanned repairs can also throw your plan off. As a result, your $200 loss can quickly jump to $1000 or more on a given month.  Not a great way to build financial stability.

The great thing about real estate investing, as opposed to other investment vehicles like mutual funds or stocks is that, for the most part, you can calculate your monthly cashflow before even buying.  With this knowledge, you shouldn’t have many surprises after your purchase.  All of the results are available to you beforehand IF you take the time to run a simple analysis.

By understanding your cashflow, you’re taking the first step in building a solid foundation of wealth.  A positive-cashflow property will add to your wealth over time by covering all your expenses with each rent payment.  Thereby allowing you to slowly build your equity along the way too.  All these gains are now the result of just your original investment.  That’s the magic of smart real estate investing!

It is worth exploring the Equity portion of the equation in a future blog.  Even this is not the end of the story of your investment!  You still have potential appreciation of the property to factor into to this winning combination.  Again, this too will require a little more discussion as we need to explore the proceeds, costs and tax liabilities upon property disposition.

But first, in my next post, I’ll discuss some key strategies to maximize and stabilize your cashflow. Until then if you need any support contact me directly.

Schedule time for a Safety Checklist

Quarterly Safety Checklist

As a homeowner, landlord or tenant, there are a number of things that should be on everyone’s quarterly checklist. This will help ensure the safety of your home and your loved ones.  It doesn’t matter who takes care of these items, as long as they are done regularly.  Set up a quarterly reminder on your digital calendar just so they don’t slip thru the cracks.

  • Check Fire Extinguishers: Fire extinguishers can save lives.  Make sure the seals are intact, look for any damage and checking the pressure by using the test indicator.  If you have not yet invested in this life saving equipment you need to know there are different types. Each style is formulated to deal with hazards in each area of your home.  For each living area/level install a 2-A:10-B:C rated extinguisher.  For larger homes it is recommended to have access to an extinguisher within 40ft.  Don’t forget to put on in your garage or workshop.  Due to the extra flammable liquids in this area you need to use a higher rated 3-A:40B-C extinguisher.  After these basic installations, extinguishers designed specifically for electrical fires and kitchen hazards are recommended.  The kitchen is the likeliest place you will have a fire, so you can help protect your home with a 711A extinguisher in this area.  To tackle fires involving energized electrical equipment, typically in the basement, an extinguisher with a rating of 1-A:10-B:C. is needed. 
  • Check Smoke & Carbon Monoxide Detectors:  Another life saving device in your home needs regular attention too.    It is super easy to test smoke and carbon monoxide detectors. Simply press and hold the test button and wait for a loud, alarm-like noise. If the sound is weak or the detector is silent, replace the batteries immediately.
  • Clean Range Hood Filter:  After removing the grease filter from your range hood, soak it in warm soapy water with some baking soda. Then scrub them with a non-abrasive brush, rinse, and dry. This method will ensure your filter is working to its full potential.
  • Change Furnace Filters: Overtime your furnace filter becomes clogged with dust, dirt, pet dander, and other particles. Replacing your filter every 3 months (or more often as needed) will ensure your furnace is running efficiently and will increase the indoor air quality of your home.
  • Clean Lint Ducts:  Lint traps can be the source of some spontaneous fires due to the back up of debris and obvious heat source.  Regular vacuuming the lint ducts and surround area of your dryer can reduce the risk of fires. Remove your lint filter from the dryer and vacuum the lint trap housing.  It is worth your time to regularly disconnect the dryer duct itself and vacuum out the full length of the duct work.
  • Check For Frayed Cords: Starting in the basement, work your way through each electronic device or appliance that is plugged in to check for any frayed cord wires or cables. If frayed, replace immediately.  It may seem tedious, but if you can detect an issue before it leads to an injury or a fire, it is time well spent.
  • Washer Checkup: Clean out your washer’s inlet filters, check for any leaks, drain out any bottom drains on your machine and run a washer cleaning cycle with the appropriate cleaning additive.  Your washing machine’s inlet filters help filter out any debris or mineral deposits from the water in the machine. It is important to regularly clean them in warm soapy water every three months and replace when necessary.  If you have leaks on your washer seals, you can contact a repair technician, or purchase replacement kits to save your floors from constant dripping water damage.
  • Inspect Caulking Around Sinks, Tubs & Showers:  A quick check the caulking around tubs, showers, and sinks to ensure there are no leaks. Leaks can result in damp patches, which can then lead to mold in your kitchen, bathroom, and laundry room. If you notice any gaps, re-caulk as soon as possible. Don’t forget to check for water around the base of your toilet. Constant dripping due to a broken or dried out wax ring can compromise the safety of your floor here too.
  • Exterior walk-about:  It is important to do a regular check of your eavestrough system and downspouts and ensure there is no water dripping or pooling near the foundation of your home.  Water management is one of the most important to ensure the longevity of your home. For the fall we have a blog that covers the 15 Step Fall Maintenance Checklist you should check out.  

Regular maintenance and these safety checks will often give you the heads up needed to plan and budget for larger updates.   If there are projects that are out of your comfort range, or you want help with completing the checklist itself, the team at  East Vista Home Services are ready to support you and book necessary service calls from qualified technicians you can trust.

Landlords and Tenants Benefit from New Amendments

Part of our mission is to keep you updated amendments to the Residential Tenancies Act. New updates come into effect on September 1, 2021.  These amendments are part of Bill 184 passed on July 21, 2020. The intent of these changes is to strengthen the Act for both Landlords and Tenants.

To summarize:

  • Landlords will have the ability to file a claim against a former Tenant. Claims can include Rent Arrears, Unit Damage, Utility Arrears and NSF charges.  The Landlord has up to one year after a Tenant has vacated to file a claim.
  • Increased compensation allowed to Tenants subject to bad faith/illegal evictions. Compensation can include damages equivalent to as much as 12 months’ rent.
  • Landlords will have the ability to file a claim for Utility Arrears. Damages to the unit caused by a current Tenant is also claimable.
  • Additional documentation required when filing for a Hearing.
  • The new legislation does not apply to issues existing before September 1, 2021.

You can read the full summary from Tribunals Ontario at this link.

Past blogs include Rental Rate Guidance for 2022.

Rental Rate Guidance for 2022 – Don’t Make Costly Mistakes

Ontario Rent Increase Rate Announced

On June 17th we saw the release of the latest guidance for Ontario’s 2022 Rental Rates. For the full Ontario Government Bulletin click here.

The guideline from this Bulletin sets rent increases for 2022 in Ontario to 1.2%.  This rate applies to most residential rental accommodations covered by the Residential Tenancies Act.  As most of you know, Ontario had frozen rent increases in 2021. This was done as a financial response to tenants dealing with COVID-19 pandemic challenges.

The Practice:
As we look to 2022, the guideline sets the maximum Landlords can raise a tenant’s rent without seeking the approval of the Landlord and Tenant Board (LTB). Variances are possible to obtain when necessary For instance, Landlords may apply for a larger increase rate after major capital work that has been completed and other specified circumstances.

The Process:
Although annual increases are allowed, rent increases are not automatic or mandatory.  Plus, to make desired increases legally, the Landlord must give the Tenant at least 90 days written notice of any rent increases. In addition, this notice must be done using the correct form, and can only impose increases after 12 months from date of tenancy.

Important consideration for Tenants: If you believe you have received an improper increase, you must report the disputed amount with the LTB within 12 months.

The Discussion
LTB notices are not likely to make the top 10 in your social feeds. As a results, we hope that by providing this and similar information as it is released will result in productive and informed discussions between Tenant and Landlord. Effective communication is an important element as you both look forward to a successful 2022 and continued partnership.

A sample calculation of a rent increase

Monthly rent was $1,000 when the lease agreement was signed June 1, 2021.
The guideline for 2022 is 1.2%. Therefore:
> an increase of 1.2% on $1,000 = $12
> $1,000 + $12 = $1,012
> The landlord could lawfully increase the rent payment 12 months later, on June 1, 2022 up to $1,012 per month.
Your landlord would need to provide you written notice at least 90 days before June 1, 2022.
As always, when you have any questions in the area of local rental levels, current property valuation or tenant management, please feel free to reach out thru any of our channels below, and we will try to get you the clarification you require.

Mortgage Rate Trends to Benefit From

Despite the current Covid challenges, the Ontario housing market continues to strengthen.  This is further assisted by historically low stimulating mortgage interest rates. The availability of such low-interest rates, seen as close to ‘free money’, added to a rebounding/relocating job market and a lower supply of homes available continue to push pricing upward.

Areas all across the country are seeing this trend.  In the GTA, many communities have substantial month over month increases in value, and other local regions have seen all-time record housing pricing including the Waterloo Region, Barrie and Ottawa.

Low interest rates are not a short term trend but rather are expected to continue thru to 2023. The prime rate in Canada is expected to remain at low levels of .25% until 2023.  As a result, fixed mortgage rates should stay in the 1.49%, +/- 0.25-0.4%, range for 5 year fixed rates.  It is unlikely to see any exceed the 2.00% level in 2021 and early 2022.

Under the current massive and unprecedented stimulus, ideas that are supportive of economic and inflationary stability will continue to be explored.  With low, or even negative GDP rates and historic low employment rates, the stock markets and housing markets continue to be at all time highs mainly due to these stimulus efforts and low, low interest rates.   The Bank of Canada has promised low rates to at least 2023 to give borrowers the confidence needed to continue the  necessary spending.

Watch the 5-year bond yields as these are market driven can indicate an upcoming change ahead of any formal decision from the Central Bank to increase their rates.  Given this, we are likely to see fixed-rate mortgages move into the low 2% range towards the middle to end of 2021 and a solid move into the 2% range in 2022.  We’ll have to wait to see what the Central Bank rate does in 2023.

Opposite rate movement would likely only happen if a new vaccine-resistant strain of the virus appears or there are more bankruptcies in the coming month than the government was expecting. 

So, from a mortgage point of view, choosing a fixed rate now between 1.49% and 2% will give you stability for the long term.  On the other hand, the variable-rate will not pose too much additional risk for increases. You may even benefit from any potential declines and variable mortgages also often have certain features that make them more flexible and feature-rich than fixed rates.  Happy mortgage shopping!

Six Reasons Spending Money on your Property Makes Sense

Property Maintenance

Real Estate investing could conjure up images of cheques rolling in non-stop while you sleep. The more properties you own the more alluring the profits.

Some investors forget that they need to sow the seeds to ensure future profit crops.  Spending money on your properties is a required element, knowing how to balance the necessary from the overspending is the trick.

Here are six reasons it’s important that real estate investors to nurture a healthy relationship with spending money and the people that will help see it spent properly in their property.

  • You can beat inflation: There is one other truth that usually holds out, wht you can buy today will more than likely cost more tomorrow.  So if a repair or upgrade is necessary to protect the money already invested in your property then better to do it sooner than later.
  • Money Well Spent: As long as you are not an impulse spender, or  splashing out money for unneeded over the top décor choices, spending money in the right place means you are directing it precisely where it is needed and not allocating to any other area of your life that does not support your property investment’s stability.  You get what you pay for.
  • You may experience a better quality of life: Whether for your own home or the home your tenants call home, they both need attention and care.  What kind of price can you place on living in a better neighborhood or securing a long term tenant.  Painting a room just the right colour to change your mood, updating to a laminate floor for easier care when you own a furry friend easier or updating the central hub of the home – with a well thought out kitchen? 
  • Choosing to help the economy exactly where you want to: As an investor you are part of the overall economy in any community you choose to invest and be part of.  Consumer spending comprises about 70% of GDP. People spent their money so that you could obtain it. Your expenditures today, although profitable for you in the long run, actually also afford someone in the community an improved qualify of life, not to mention the goodwill with your tenant.  Now that’s a doubly good feeling!
  • You can actually buy time: I have been called cheap, although I prefer frugal, but when it comes to how I invest MY time, well then the cost:reward equation becomes an even more serious endeavour.  I’m sure most home owners could also take on many of the little jobs around an investment property yourself, but what is this task costing you beyond just the gas and supplies?  What else could you have used that time for?  Who could you have spent time with?  What could you have learned?  Could you have made more money elsewhere? There is a time to let others take over these tasks for a more meaningful life.
  • Spending is just more fun: You, like me, may have a partner, friend or relative that has demonstrated this belief and skill many times over with zest.  Overspending is never the goal, but at some point in life you have reach a state of financial freedom and money and your future security no longer carries the same worry it did when you were 20.  Now may be the time you reflect “What am I doing all of this for?” and “If not now, when?”  Just as practical items like a good mattress improves your sleep and health, so to can practical property management partnership and well planned investments into your property can enhance state of mind by eliminating the worry, freeing you for more pleasurable activities.  You deserve it.

Ideally, with each successive year of your life, you will actually spend more, not less. It’s a responsible approach — as long as your income rises at the same or greater rate.

Delayed gratification may matter when you’re younger, but how long will you defer your best life? Let’s all pledge to ‘pay ourselves first’!  If you have entered the real estate investor arena you likely will not have to delay as much gratification as others when you decide that well-directed spending is truly the best way to the finish line.  Remember “Wealth is not his that has it, but his that enjoys it.” [Ben Franklin]

5 Easy Steps to the Lowest Taxable Rental Income

Income Gain or Loss SeeSaw

The CRA’s ‘Statement of Real Estate Rentals’ (Form T776) is recommended to be completed for each Canadian rental property you own and attached with your annual personal tax filing. Simply follow these 5 easy steps or ensure your bookkeeper or tax accountant have all the necessary details to so on your behalf.

Step 1: Identification & Period Covered
Enter your name and social insurance number at the top of the form.

Here you will also enter the investment period. For example, set the start date to January 1st if you owned the property before this taxation year, and the end date, December 31 if you still own the property at the end of the tax year.  If you acquired the property during the tax year simply enter the official purchase date you took ownership.  If this is the case, there are special half-year rules that will apply to you.

Step 2: Ownership
This is an important step as you detail any co-owners or partners and will affect tax reported on your personal taxes.  Assuming you are the sole owner you would simply enter 100%. However, if there are other owners in addition to yourself, enter their details and % they share ownership and any gains or losses in the property for tax purposes.

Step 3: Property Identification & Gross Rental Income
This section of Form T776 allows you to record the property address and establish if there is just 1 ‘rental unit’ within your address such as a condo you rent.  Or possibly you have a house that has an upstairs and downstairs renter which constitute ‘2 rental units’.  If you are more established investor, you might own an apartment with 26 renters or ‘units’. Whatever level of investor you are, capture all rent payments you collected from renters to establish your Gross Rental Income.

Step 4: Net Rental Income before CCA
To complete this section you need to first understand if an expense in question is a ‘Current’ expense or ‘Capital’ expense.  Current expenses, provide short term benefits such as general maintenance, and can be deducted from your rental income.  Capital expenses, provide a long term benefits for your property such as a bathroom renovations.  These expenses are added to the ACB of your property to reduce future Capital Gains.  Page 14 of this CRA Explanation Document provides a useful chart to help you determine which they are.

List of Expenses:  Collect your receipts and enter all the ‘Current’ expenses incurred in the tax year.  These would include common deductions such as:

  • Advertising – you may also deduct finders’ and referral fees that secure tenants
  • Insurance – remember to only deduct the portion of the coverage that applies to the tax year.
  • Interest and bank fees – any Mortgage or Line of Credit interest linked to your property and simple account fees that support your investment
  • Office expenses – all consumables used directly to support your investment, do not include ‘capital’ expenditures such as calculators, filing, chairs or a desk.
  • Professional fees – not only can you deduct cost of Accountants and Bookkeepers to manage your books and prepare your taxes, you can also deduct all legal and related fees to create leases and collect rents. Reminder, legal fees when buying are selling are considered Capital expenses.
  • Management and administration fees – this would include all payments to property management companies or other agents employed to help secure and manage tenants. 
  • Maintenance – this includes all preventative and repair costs incurred in the upkeep of your property.  With one exception, you cannot claim your own labour, so you may as well hire out and keep your time for personal pursuits.
  • Salaries and Benefits – don’t forget to include any employer contribution portions
  • Property Taxes
  • Travel expenses – all reasonable expenses to get you to the property to oversee repairs or collect rents are deductible.  Lodging overnight is not, neither would be flights if your property is in another province.  It is not ‘reasonable’ to expect you to collect rent personally.
  • Utilities – any utilities required to maintain property that tenant is not contracted to pay
  • Motor Vehicle expenses – If your property is in the general area you live and do all the repairs yourself, or need to transport tools to the location, you may deduct this portion of your vehicle expenses, if you track all business and personal expenses. Make sure you do not consider mileage for collection of rent nor can you include any CCA deductions for this personal vehicle.
  • Other allowable expenses – Landscaping fees, condo fees and lease cancellation are the most common.

It is also important to remember that in addition to your own labour, you cannot claim Land Transfer Costs, Mortgage principal payments nor any penalties on your notice of assessment.